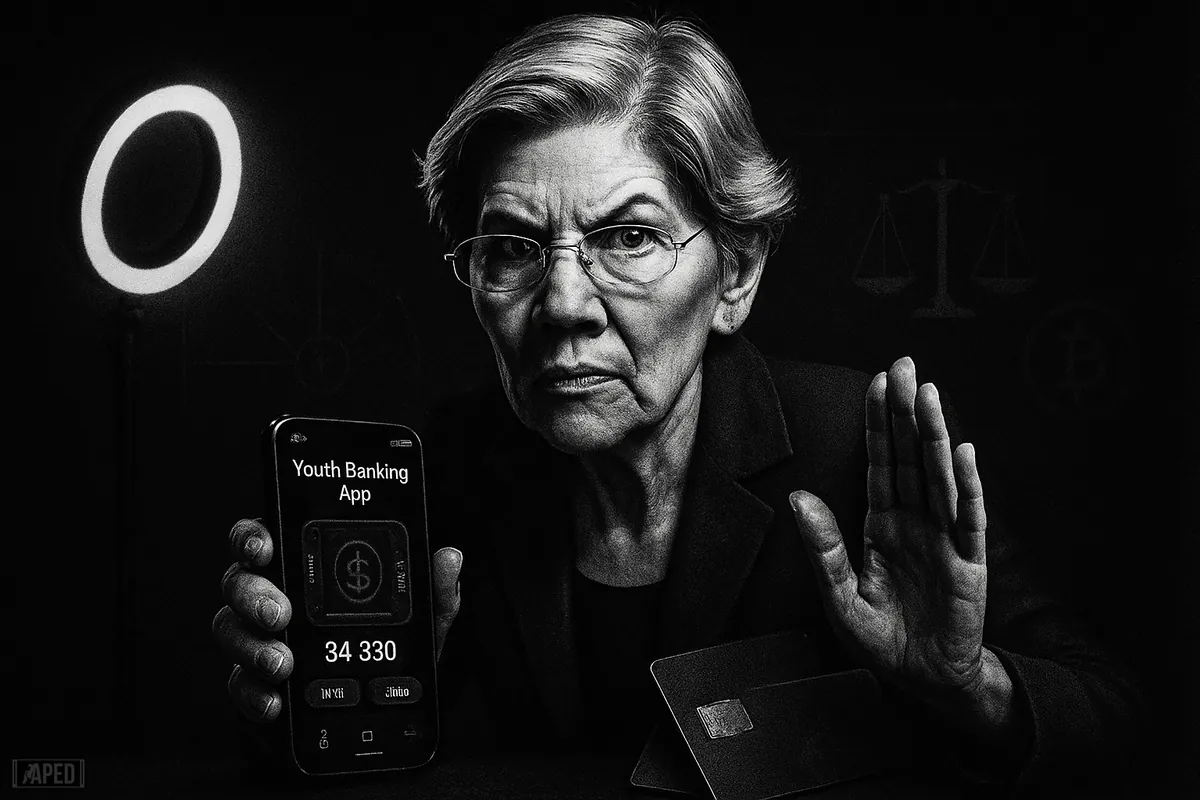
MrBeast is trying to move from YouTube giveaways into teen banking, and Senator Elizabeth Warren is already asking whether Crypto will be slipped into the mix. The catalyst is a reported $200 million deal tying Beast Industries to fintech app Step, a youth-focused banking platform that Warren says could expose children and teenagers to speculative digital assets. [1]
Enjoy articles without ads?
Register for free and get unlimited access to all articles.
Warren's core concern
Warren has sent questions to Beast Industries over its relationship with Step, focusing on whether the app could be used to marketCrypto or related investment products to younger users. That is the nub of it. Not whether MrBeast can launch another consumer brand, but whether one of the internet's biggest youth magnets ends up funnelling kids toward a market regulators still struggle to police properly. [2]
Her warning is politically on-brand, but it is not baseless. Step built its name around financial tools for teens, including spending cards and app-based money management. Add a creator with MrBeast's scale, and the distribution engine becomes enormous. That matters more than the branding fluff. When a celebrity-backed fintech targets a young audience, every product adjacency gets a harder look, especially crypto.
Why crypto is the flashpoint
Crypto is not the confirmed product here. That distinction matters. Warren's concern is about the apparent possibility that digital assets, trading features, or crypto-linked promotions could make their way into a platform used by minors or very young adults.
That fear is easy to understand. The line between banking, investing, rewards and speculation has become blurry in consumer fintech. One minute it is savings tools, the next it is stock slices, stablecoin rails, token rewards, or some "learn and earn" wrapper that looks educational until markets go sideways. For adults, that is a risk disclosure issue. For kids, it becomes a consumer protection issue very quickly.
The MrBeast factor changes the equation
MrBeast is not just another influencer licensing his face. He has one of the largest youth-heavy audiences online, and that gives any financial product he touches unusual reach. Regulators tend to care less about crypto in the abstract than about distribution, incentives and who is being targeted. On that basis, this is a proper live issue. [3]
A traditional bank ad aimed at families is one thing. A personality-driven app ecosystem, built around parasocial trust and huge social engagement, is another. Young users do not necessarily separate entertainment branding from financial judgment. That is where critics think the setup gets dodgy.
Step's position in the market
Step is known as a banking app designed to attract younger users before they graduate to full-service finance. That strategy has always made commercial sense. Acquire customers early, hold them for years. But it also invites scrutiny when the product stack broadens beyond basic payments and budgeting.
If Beast Industries is helping Step scale distribution or deepen engagement, lawmakers will want details on product design, data use, promotions and any plans involving digital assets. The exact mechanics matter more than the headline partnership.
What lawmakers are likely asking behind the scenes
Warren's intervention suggests a few specific pressure points. First, whether minors could be shown crypto content directly or indirectly. Second, whether rewards, referrals or creator-led promotions could nudge inexperienced users into speculative behaviour. Third, whether disclosures would be robust enough for a user base that may not fully understand volatility, custody risk or platform risk.
That last point is often where fintechs get caught out. Plenty of apps present risk in clean legal language while making the front-end feel frictionless, social and game-like. Crypto bolted onto that model can become a bit of a mess, especially if the audience is young and trust is borrowed from a celebrity rather than earned through financial literacy.
The bigger regulatory backdrop
This is landing at a time when US policymakers remain split on how digital assets should be marketed and to whom. Even as parts of Washington have become more open to crypto infrastructure and payments innovation, scrutiny stays high where retail consumers are concerned. Put children, influencers and a fintech wrapper into the same story, and the temperature rises fast. [4]
Warren has built much of her crypto critique around consumer harm, scams and weak safeguards. A MrBeast-linked banking app gives her a high-visibility example to test those arguments. It also puts pressure on the company to show that no crypto push is planned, or that strong guardrails exist if any digital asset features are under consideration.
What is not clear yet
Several important facts remain unconfirmed publicly. It is not clear whether Step plans to offer direct crypto trading, crypto rewards, wallet functionality, stablecoin features, or simply has broad optionality that worried lawmakers. It is also not clear how much operational control Beast Industries would have over product direction versus brand and distribution. [5]
That uncertainty is exactly why the story matters. In crypto, markets often react to products after launch. Regulators prefer to intervene at the design stage, before a mass consumer funnel is built.
Why it matters
This is bigger than one creator deal. If Warren's warning gains traction, it could shape how fintechs structure creator partnerships where younger users are involved. Expect harder questions around age gating, disclosures, financial promotions and whether crypto features belong anywhere near youth-focused apps.
For Beast Industries, the invalidation line is simple. If the company can show the Step tie-up has no crypto distribution angle, or that any digital asset exposure is firmly walled off from minors, the political heat may cool. If not, this could become a test case for how far regulators will go to stop influencer-led crypto from reaching the next generation before they are old enough to know a punt from a proper product.
Your reviews help us improve the quality of both current and future articles. All reviews are public and visible to other readers. We use both ratings and comments to improve future articles and to revise any articles that do not meet our standards.
 See more like this on Google