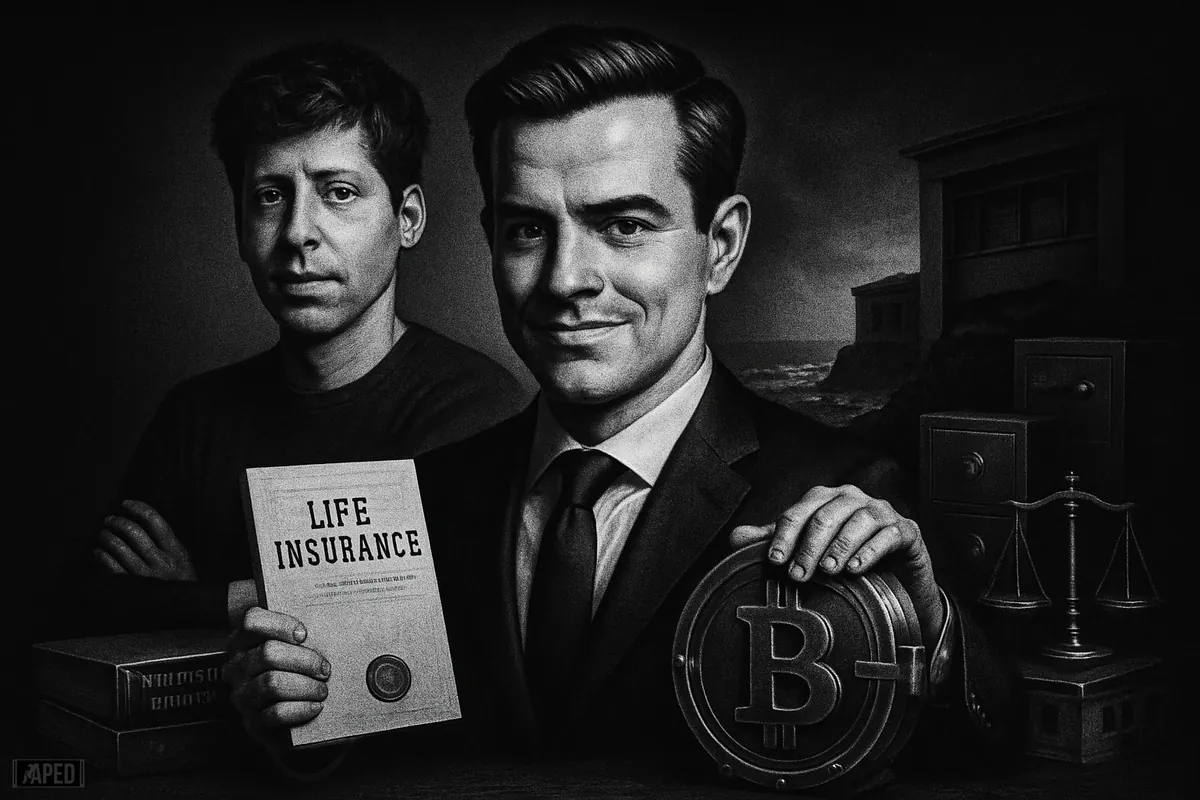
Crypto finally found another sentence nobody expected to read with a straight face: Bitcoin$83,080.62 life insurance is having a moment.
Meanwhile, a Bermuda-based insurer that operates entirely in Bitcoin$83,080.62, said Friday it raised $37.5 million from existing backers as wealthy clients outside the US look for a regulated way to hold and eventually pass on BTC. The company says the new round pushes its total funding past $180 million. [1]
Enjoy articles without ads?
Register for free and get unlimited access to all articles.
The more interesting signal is not celebrity-adjacent cap table trivia. It is that this round came from existing investors doubling down rather than a brand-new cast trying to catch a narrative. In private markets, insider support often carries more weight than a flashy announcement because it suggests current stakeholders have seen enough operating data to keep writing checks.
According to the company, demand has been rising across Asia, Europe, and the Middle East, where macro instability and cross-border wealth planning are pushing affluent Bitcoin holders to look beyond simple self-custody. Put plainly, some families already have a sizable BTC bag and are now asking a very unglamorous but important question: what happens to it when the owner dies? [3]
Meanwhile's core thesis is simple. Bitcoin holders may be comfortable storing wealth in BTC, but transferring that wealth cleanly to heirs is a separate problem. Wallet keys can be lost, inheritance processes vary by jurisdiction, and traditional estate structures do not always map neatly onto crypto-native assets.
CEO and co-founder Zac Townsend framed the gap directly in the company's announcement, saying wealthy families already hold Bitcoin$83,080.62 but have lacked a regulated way to pass it on. He also said brokers approached Meanwhile because clients were already asking for this kind of product, which matters. Insurance is a broker-driven business, and organic demand from advisers usually says more than CT chatter. [1]
That positioning also helps explain why the company is targeting estate and succession planning rather than trying to sell a broad retail dream. This is not a mass-market term policy for someone buying their first satoshis. It is a financial planning product aimed at high-net-worth households that want Bitcoin exposure preserved across generations.
How Meanwhile's products are structured
Earlier this year, Meanwhile launched BTC Life 1-Pay, a single-premium whole life policy designed for high-net-worth clients outside the United States. Single-premium means the policy is funded upfront in one payment rather than through recurring contributions. Whole life means it is meant to remain in force permanently, assuming policy terms are met.
That product followed the company's earlier BTC 10-Pay line, which was designed for US taxpayers. The two-product setup suggests Meanwhile is building around regulatory and tax distinctions rather than forcing one global template onto every customer. That is less sexy than "disruption," but probably more durable.
Policies can be owned by individuals, trusts, or companies, according to the firm. That detail is easy to miss, but it is central to the value proposition. Trust and corporate ownership make these policies more usable in real estate planning structures, especially for families with assets spread across jurisdictions. [4]
The timing says a lot about where crypto wealth is maturing. A few cycles ago, the industry's flagship products were mostly about getting exposure. Spot, perpetuals, staking, yield. Now the stack is widening into boring-finance territory: insurance, recovery, inheritance, compliance, and wealth transfer.
That shift is actually a bullish sign for infrastructure, even if it is not the kind that sends floor prices flying in a Discord. Mature capital eventually demands mature wrappers. If a family office or wealthy individual wants to keep Bitcoin as part of a long-term balance sheet, they also want legal clarity, succession planning, and regulated claims processes.
Macro instability is part of the backdrop here too. Meanwhile explicitly tied recent demand to broader uncertainty, especially in international markets. When local currencies, tax rules, or political conditions feel shaky, globally portable digital assets become more attractive. But portability alone is not enough if the asset becomes operationally fragile at the point of inheritance. [1]
A small niche, but a real one
Meanwhile did not disclose exact revenue or underwriting figures, but it said net long-term underwriting income has already surpassed last year's total and is on pace to more than double in 2026. Without hard numbers, that claim is impossible to fully verify from the outside. Still, it suggests the company is seeing more than just curiosity clicks from brokers and clients. [3]
The life insurance market itself is huge, but crypto-native insurance remains a narrow slice. That is likely to stay true for a while. Most holders do not need a Bitcoin-denominated whole life product, and many retail users still struggle with much simpler financial planning basics. Meanwhile's opportunity looks less like a mass consumer wave and more like a specialized category with wealthy early adopters.
That can still be a good business. Financial products aimed at concentrated pools of capital do not need millions of users to matter. They need trust, regulatory credibility, and enough product-market fit to become the default option for a very specific buyer.
The wider insurance lane is opening up
Meanwhile's raise also lands during a broader push to professionalize crypto risk management. Earlier this year, insurance broker WTW expanded its digital asset protection offerings through the acquisition of crypto insurance platform Redefind. That service focuses on a different problem set, including forensic investigation, asset tracing, and legal recovery after theft or loss.
The contrast is useful. One side of crypto insurance is about recovery after something goes wrong. The other, where Meanwhile sits, is about orderly transfer when life happens exactly as it always does. Together, they point to a sector moving from speculative edge case toward fuller financial plumbing.
Meanwhile's $37.5 million raise is not just another venture round with familiar logos on the slide. It is a bet that Bitcoin wealth is sticking around long enough to require inheritance planning, policy design, and regulated handoff mechanisms.
For readers, the practical takeaway is simple: watch whether Meanwhile can translate niche demand into visible scale, especially outside the US where it says momentum is strongest. The main catalyst is continued adoption among brokers and high-net-worth clients. The main risk is that a highly specialized product can stay specialized for longer than investors hope.
Still, when crypto's next growth area involves trusts, underwriting, and succession planning, that is a pretty clear sign the industry is growing up, even if it still insists on posting through it.
Your reviews help us improve the quality of both current and future articles. All reviews are public and visible to other readers. We use both ratings and comments to improve future articles and to revise any articles that do not meet our standards.
 See more like this on Google